Newsroom · Sioux Falls
Your 2027 Medicare Part B premium isn't official yet: what to budget during this year's AEP
CMS's real number doesn't arrive until mid-November — a month after Sioux Falls starts picking 2027 coverage on October 15.
The bottom line
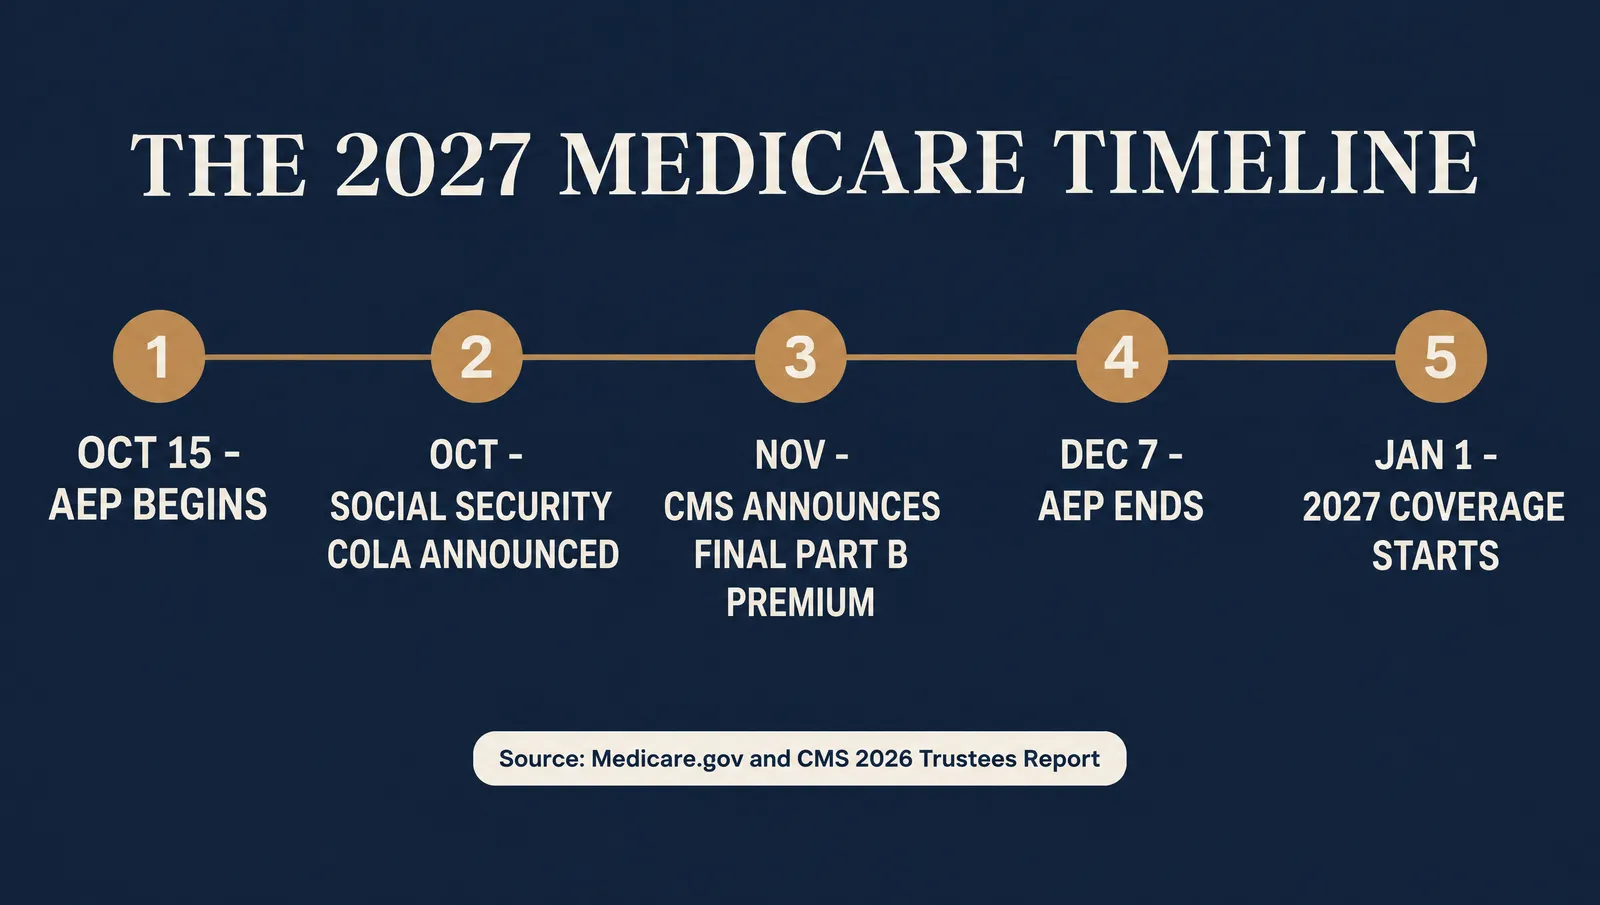
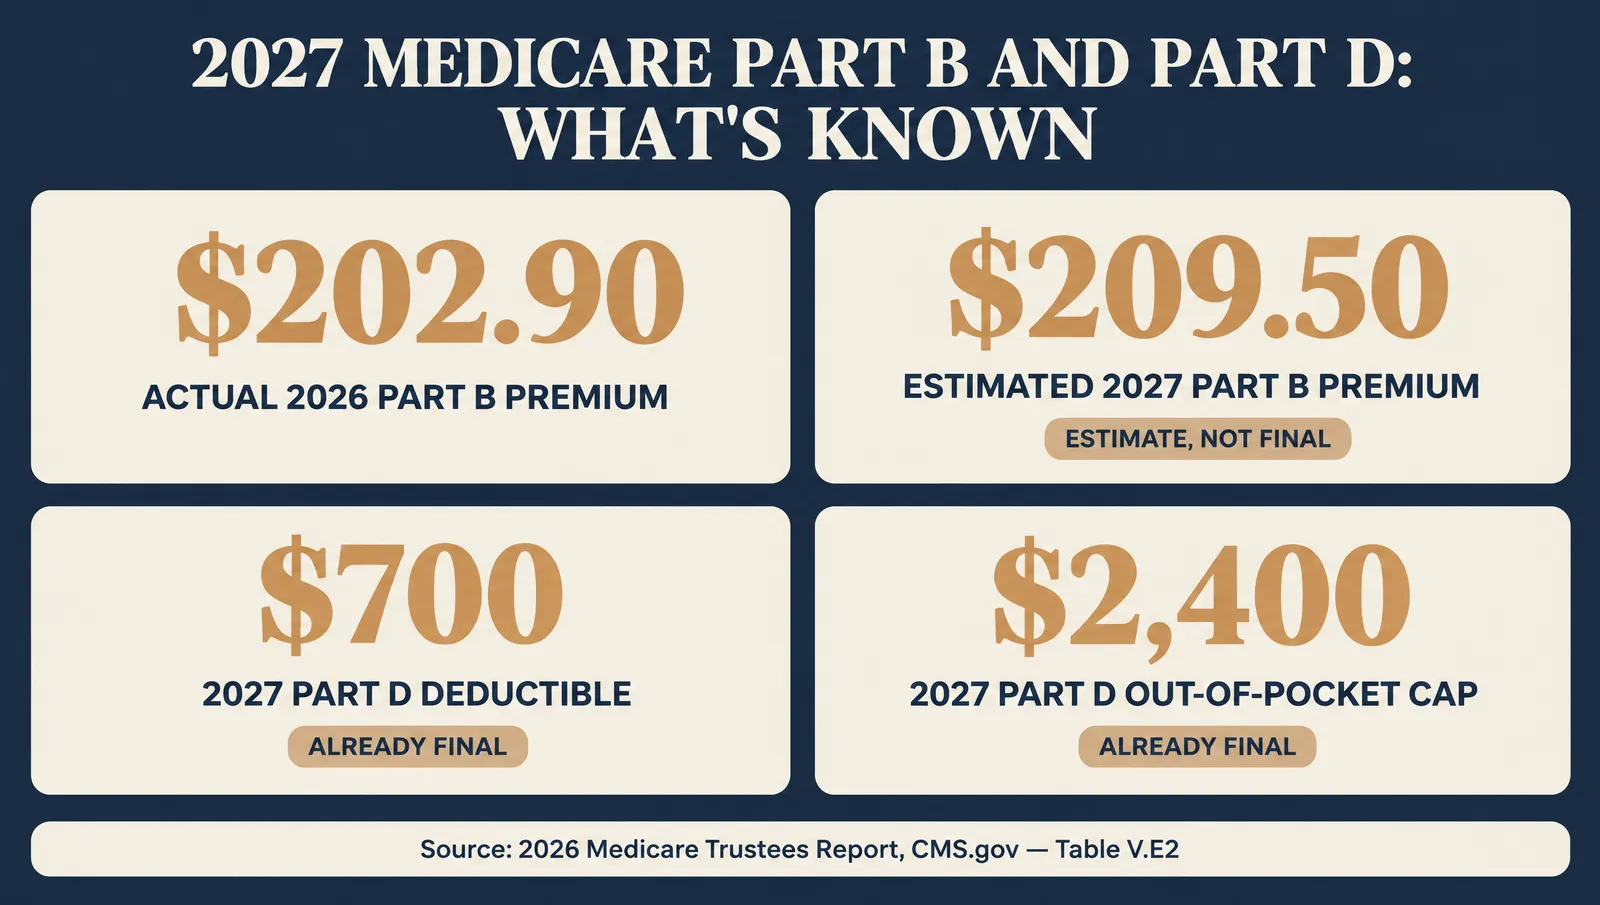
- The 2026 Medicare Trustees Report (published June 9, 2026) estimates the 2027 Part B premium at $209.50 a month, up from the confirmed 2026 premium of $202.90 — but it's a projection, not the final number.
- CMS typically doesn't announce the official figure until mid-November — it confirmed the 2026 premium on November 14, 2025, a full month after that year's Annual Enrollment Period had already opened.
- This year's AEP runs October 15 through December 7, per Medicare.gov — meaning you'll likely choose your 2027 coverage before the real Part B number exists.
- Two 2027 Part D figures are already locked in, not estimates: a $700 deductible ceiling and a $2,400 out-of-pocket cap, per the same Trustees Report.
- The Part B premium applies to every one of the 39,532 Medicare beneficiaries in Minnehaha County — including anyone on a $0-premium Medicare Advantage plan.
The honest answer, in mid-September, is that nobody can hand you a confirmed 2027 Medicare Part B premium — the best available number is a projection of $209.50 a month from the 2026 Medicare Trustees Report, and the Centers for Medicare & Medicaid Services won't finalize the real figure until its usual November announcement. That gap matters this year more than most, because Sioux Falls starts choosing 2027 Medicare Advantage, Medigap, and Part D coverage on October 15 — weeks before the official cost of the one piece of Medicare nobody gets to opt out of is actually known.
Every figure in this guide was fetched and confirmed live this week: CMS's own 2026 Parts A & B Premiums and Deductibles fact sheet, the full text of the 2026 and 2025 Medicare Trustees Reports (the federal government's own actuarial projections for the Medicare program), and Medicare.gov's Open Enrollment pages. Plan data for Minnehaha County comes from this site's own CMS PY2026 Medicare Advantage Landscape file. Nothing here is recalled from memory, and nowhere does this guide guess at a number it can't source.
What we actually know right now
Start with the plain facts, because the rest of this guide builds on them. In 2026, the standard monthly Medicare Part B premium is $202.90 and the annual Part B deductible is $283, confirmed by CMS on November 14, 2025, per CMS — 2026 Medicare Parts A & B Premiums and Deductibles (Fact Sheet). For 2027, the best available number is a projection, not a confirmed figure: the 2026 Medicare Trustees Report — the federal government's own annual actuarial analysis of the Medicare trust funds, published June 9, 2026 — states plainly, "In 2026 the monthly Part B premium rate is $202.90 ... The estimated monthly premium for 2027 is $209.50."
Two terms worth knowing before you read on
- Medicare Trustees Report: an annual, 10-year financial projection for the Medicare trust funds, prepared by the Boards of Trustees (the Treasury Secretary, Labor Secretary, HHS Secretary, Social Security Commissioner, and the CMS Administrator, plus public trustees). It projects costs; it does not set them.
- AEP (Annual Enrollment Period): the October 15 – December 7 window when anyone with Medicare can change their Medicare Advantage, Medigap, or Part D coverage for the following year.
So the honest framing for AEP 2026 is this: you have a well-sourced estimate for what 2027 will cost you in Part B premium, and a real, if unofficial, planning number. You do not yet have the number CMS will actually charge you starting January 1, 2027.
Trying to budget for 2027 before the real numbers land?
You can absolutely work through the estimate yourself with the numbers below. If you'd rather talk it through with someone local, that's what our annual coverage review is for — no cost to you.
Book a conversation →Why nobody can give you the final number in September
This isn't a case of CMS sitting on information. The Part B premium for a given year genuinely isn't finalized until the fall before it takes effect, because it's calculated from real, current-year program costs — enrollment, spending trends, and the size of the reserve the Supplementary Medical Insurance trust fund needs to carry. CMS can't lock in 2027's number in September 2026 any more than a business can finalize next year's insurance renewal before this year has finished playing out.
What changes year to year is the timing gap between that calculation and your own Medicare decision. This year, the gap is unusually visible: Medicare's Annual Enrollment Period opens October 15 and runs through December 7, per Medicare.gov — Open Enrollment — the one stretch of the year when everyone with Medicare can change their coverage for the following January. CMS's own "Remember Key Medicare Dates" fact sheet confirms the same window and adds that changes made during it take effect January 1, per Medicare.gov — Remember Key Medicare Dates (CMS Product No. 12192) (CMS Product No. 12192, September 2025). But CMS's Part B premium announcements have landed in mid-November in recent years — it confirmed the 2026 figure on November 14, 2025, a full month after that AEP had already opened.
"I'll just wait for the real number"
- Waiting past December 7 means missing AEP entirely for most changes
- The Medicare Advantage Open Enrollment Period (Jan 1–Mar 31) only lets people already on a Medicare Advantage plan switch plans or return to Original Medicare
- It doesn't let you newly join a Part D plan from Original Medicare, or add a Medigap policy on your own timeline
Budget on the estimate, adjust if needed
- Use the Trustees Report's $209.50 figure as your planning number now
- Make your AEP choice on schedule, based on the plan-level facts you do know
- Recheck the math once CMS's real number lands — you'll usually still have days to weeks left in the window
There's a real financing mechanism behind the wait, not just bureaucratic timing. The Trustees Report explains that Part B premiums and the matching general-fund transfers "are established annually to cover the expected costs for the upcoming year" — and because that process is designed to be self-correcting, it has to run on real, current data. If costs come in higher than expected, future rates absorb the difference; if lower, future rates ease off. That annual reset is also why Part B carries a comparatively small contingency reserve, per the same report — Medicare doesn't need to bank years of cushion the way its Hospital Insurance trust fund does, because Part B's price simply gets recalculated every single year against real numbers. The premium literally cannot exist in final form until the year it's calculated for is nearly over.
Where the $209.50 estimate actually comes from
This isn't a number pulled from a financial-media headline — it's sitting in the government's own projection table. Table V.E2 of the 2026 Medicare Trustees Report, titled "SMI Cost-Sharing and Premium Amounts," lays out the historical Part B premium and deductible back to 1970 and then projects it forward a decade under what the report calls its "intermediate" (middle-of-the-road) assumptions:
| Calendar year | Part B standard monthly premium | Part B annual deductible | Status |
|---|---|---|---|
| 2025 | $185.00 | $257 | Final (actual) |
| 2026 | $202.90 | $283 | Final (actual) |
| 2027 | $209.50 | $292 | Estimate |
| 2028 | $224.50 | $313 | Estimate |
Source: 2026 Annual Report of the Boards of Trustees of the Federal Hospital Insurance and Federal Supplementary Medical Insurance Trust Funds, Table V.E2, report page 207 (published June 9, 2026). 2025 and 2026 figures cross-checked against CMS — 2026 Medicare Parts A & B Premiums and Deductibles (Fact Sheet), published Nov. 14, 2025.
Read that table carefully and it tells you two things at once: the 2027 Part B premium estimate ($209.50) and the 2027 Part B deductible estimate ($292) sit in the same "Intermediate estimates" section as 2028 through 2035 — years nobody expects CMS to have finalized yet. The 2026 figures next to them, by contrast, are the same numbers CMS already confirmed in its November 2025 fact sheet. The table itself is telling you which rows are real and which are still forecasts.
Why this estimate keeps moving
If you compare this year's Trustees Report to last year's, the 2027 number itself has already moved once — which is worth knowing before you treat $209.50 as gospel. The 2025 Medicare Trustees Report, published a year earlier, projected the 2027 Part B premium at $218.60. A year later, with a full additional year of real program data to work from, the 2026 report revised that estimate down to $209.50 — a $9.10 swing on a number describing a year that still hasn't happened.
The same 2025 report also estimated what 2026 itself would cost: $206.50 a month. The actual, CMS-confirmed 2026 premium came in at $202.90 — $3.60 lower than the Trustees had projected a year ahead of time, even for the nearer-term year. That's not a knock on the Trustees' methodology; a 10-year actuarial projection is built to be revised as real data replaces assumptions. It's simply the reason this guide keeps calling $209.50 an estimate instead of a fact.
Source: 2025 Annual Report of the Boards of Trustees of the Federal Hospital Insurance and Federal Supplementary Medical Insurance Trust Funds and 2026 Annual Report of the Boards of Trustees of the Federal Hospital Insurance and Federal Supplementary Medical Insurance Trust Funds, both Table V.E2 (bars scaled to a $252 maximum for this chart).
The practical lesson: treat any pre-November Part B number, including this one, as a real but moving target. It's still the single best-sourced figure available in September — a government actuarial estimate beats a guess — but it is not the number on your 2027 Medicare bill.
The premium's climb, in real dollars
Zoom out from year-to-year estimates and a different, steadier pattern shows up — one that matters more for a household budgeting on a fixed retirement income than any single year's projection. The same Trustees Report table that projects 2027 also carries the confirmed history back decades. Here's the last ten years of actual, CMS-finalized standard Part B premiums:
| Year | Part B standard monthly premium | Year-over-year change |
|---|---|---|
| 2016 | $121.80 | — |
| 2018 | $134.00 | +$12.20 over 2 years |
| 2020 | $144.60 | +$10.60 over 2 years |
| 2022 | $170.10 | +$25.50 over 2 years |
| 2024 | $174.70 | +$4.60 over 2 years |
| 2026 | $202.90 | +$28.20 over 2 years |
Source: 2026 Annual Report of the Boards of Trustees of the Federal Hospital Insurance and Federal Supplementary Medical Insurance Trust Funds, Table V.E2, report page 207 (historical figures are CMS-finalized, actual amounts).
Ten years, from $121.80 to $202.90 — a $81.10 increase, or about 67%, over a decade in which Social Security's own cost-of-living adjustments haven't always kept pace in a given year. That climb isn't smooth: 2024 barely moved, while 2022 and 2026 both carried real jumps. It's also the reason this guide keeps circling back to the same point — the Part B premium isn't a rounding error in a Medicare budget. For someone relying mainly on Social Security, a $17.90 jump in a single year, like 2025 to 2026, is a real, felt change, and it's worth knowing where 2027 is likely to land before AEP closes rather than after.
A worked example: one Sioux Falls retiree's 2027 math
Numbers land differently in a story than in a table alone. Take a composite, illustrative Sioux Falls retiree — not a real client — comparing a 2026 Medicare Advantage plan cost to a realistic 2027 planning estimate, using only sourced figures from this guide.
Her 2026 math: she's enrolled in Align ChoiceElite (PPO), a real Minnehaha County plan carrying a $66 monthly plan premium for 2026, per the CMS PY2026 Landscape file. Add the standard $202.90 Part B premium, and her total monthly Medicare cost for 2026 is $268.90.
Her 2027 planning estimate: assume her plan premium holds roughly flat — a real possibility, since plan premiums move independently of Part B and won't be confirmed until her 2027 ANOC arrives — and pencil in the Trustees Report's $209.50 Part B estimate. That puts her planning total at roughly $275.50 a month, a $6.60 increase driven entirely by the still-unofficial Part B side of the math.
If CMS's real November number comes in a few dollars either side of $209.50 — which, per the track record above, is a realistic range — her actual 2027 total shifts by roughly that same few dollars, not by a figure large enough to change which plan fits her. That's the practical value of doing this math now: it tells her the Part B uncertainty is real but small relative to her overall decision, so she can choose her 2027 plan on the parts of the picture that are fully known — network, drug formulary, star rating — without waiting on Washington.
What's already final for 2027, and what's still a guess
Not every 2027 Medicare cost figure is up in the air. Buried in the same Trustees Report table is a footnote that's easy to miss and genuinely useful: two of the 2027 Part D figures are marked "This amount has already been finalized" — a different, firmer status than the Part B numbers sitting right next to them.
| 2027 figure | Amount | Status |
|---|---|---|
| Part B standard monthly premium | $209.50 | Estimate |
| Part B annual deductible | $292 | Estimate |
| Part D annual deductible (ceiling) | $700 | Already final |
| Part D out-of-pocket (catastrophic) cap | $2,400 | Already final |
Source: 2026 Annual Report of the Boards of Trustees of the Federal Hospital Insurance and Federal Supplementary Medical Insurance Trust Funds, Table V.E2 and its footnote 4, report pages 207–208.
That's genuinely useful for planning: your 2027 drug-cost ceiling is already locked in at $2,400, up from the $2,100 cap in 2026, per this site's own CMS-sourced 2026 figures. So is the $700 Part D deductible ceiling. If drug costs are the bigger worry in your household, you can plan around those two numbers with real confidence today. The Part B premium and deductible are the pieces still waiting on CMS's November math.
If you're a higher earner: IRMAA in 2027
If your income puts you above the standard Part B bracket, you're already paying an Income-Related Monthly Adjustment Amount, or IRMAA — a surcharge added on top of the standard premium, based on your tax return from two years earlier. For 2026, using your 2024 income, the brackets and surcharges are set and published:
| 2026 tier | Individual income | Monthly surcharge | Total monthly premium |
|---|---|---|---|
| Standard | Up to $109,000 | $0 | $202.90 |
| Tier 1 | Up to $137,000 | $81.16 | $284.06 |
| Tier 2 | Up to $171,000 | $202.90 | $405.80 |
| Tier 3 | Up to $205,000 | $324.64 | $527.54 |
| Tier 4 | Up to $500,000 | $446.38 | $649.28 |
| Tier 5 (top) | Above $500,000 | $486.96 | $689.86 |
Source: CMS — 2026 Medicare Parts A & B Premiums and Deductibles (Fact Sheet), plan year 2026, 2-year income lookback (2024 tax return).
For 2027, the same Trustees Report table that projects the base premium also projects IRMAA surcharges, in Table V.E3 — and the same "estimate, not final" caveat applies:
| 2027 IRMAA tier (estimate) | 2026 individual income equivalent | Estimated monthly surcharge |
|---|---|---|
| 35% tier | $109,001–$137,000 | $83.70 |
| 50% tier | $137,001–$171,000 | $209.40 |
| 65% tier | $171,001–$205,000 | $335.10 |
| 80% tier | $205,000–$499,999 | $460.70 |
| 85% tier | $500,000+ | $502.60 |
Source: 2026 Annual Report of the Boards of Trustees of the Federal Hospital Insurance and Federal Supplementary Medical Insurance Trust Funds, Table V.E3, report page 209. Income brackets shown are the 2026 published thresholds for reference; 2027 thresholds are typically indexed and confirmed alongside the premium each November.
If you were in, say, the 50% tier in 2026 paying $405.80 total, the Trustees Report's estimate would put your 2027 total near $209.50 plus $209.40, or roughly $418.90 — again, a planning number, not a bill. IRMAA is determined by the Social Security Administration based on your tax return, and it's appealable if a life event — retirement, a spouse's death, a work reduction — has since lowered your income; Medicare.gov's costs page covers the appeal process, per Medicare.gov — Medicare costs.
Why this matters even with a $0 Medicare Advantage plan
Here's the part that catches people during AEP: the Part B premium isn't something a Medicare Advantage plan replaces or absorbs. It's a separate, mandatory federal premium that every Part B enrollee pays directly (usually deducted from Social Security), on top of whatever a Medicare Advantage or Part D plan charges. A "$0 premium" Medicare Advantage plan means the plan itself adds nothing — not that Medicare itself is free.
That's true for every one of Minnehaha County's Medicare beneficiaries, and Lincoln County's next door, regardless of which of the county's plans they pick. Minnehaha County carries 39,532 Medicare beneficiaries and Lincoln County another 12,719, per CMS Medicare Monthly Enrollment by County (2026) — over 52,000 people in the immediate Sioux Falls metro alone who will feel whatever the final 2027 Part B number turns out to be, on top of their plan choice. Here's the county's 5-plan standard Medicare Advantage PPO roster for 2026, for scale:
| Plan | Carrier | 2026 plan premium | Stars | Stability |
|---|---|---|---|---|
| Aetna Medicare Signature (PPO) | Aetna / CVS | $0 | 3.5★ | Average (3.5★) |
| Align ChoicePlus (PPO) | Sanford Health | $0 | 3.5★ | Average (3.5★) |
| Aetna Medicare Enhanced Extra (PPO) | Aetna / CVS | $52.00 | 3.5★ | Average (3.5★) |
| Align ChoiceElite (PPO) | Sanford Health | $66.00 | 3.5★ | Average (3.5★) |
| Blue Medicare Advantage Enhanced (PPO) | Wellmark / BCBS | $80.00 | 3.5★ | Average (3.5★) |
Source: CMS Medicare Advantage / Part D Landscape (PY2026) & CMS Medicare Advantage & Part D Star Ratings (2026), Minnehaha County, plan year 2026. Two of these five carry a $0 plan premium — and every enrollee on all five still owes the separate Part B premium.
The number that actually decides your total 2027 Medicare cost is the Part B premium (still an estimate) plus whatever your specific plan charges (usually known now, for 2026 plans, with 2027 figures arriving on each plan's own Annual Notice of Change). Neither number alone tells the whole story.
Turning 65 in early 2027?
This same estimate applies to you even before you're enrolled. Your Initial Enrollment Period runs three months before your 65th birthday month, through three months after, and your Part B premium starts at whatever CMS confirms for 2027 — the $209.50 figure in this guide is your best current planning number, same as everyone already on Medicare. If you're new to this, our turning-65 consultation walks the whole enrollment timeline, not just the cost side.
How to budget for 2027 without the final number
You don't need the official CMS figure to make a sound AEP decision this fall. Here's the method:
- Start with $209.50 as your Part B planning number. It's the best-sourced estimate available, from the government's own actuarial report, not a guess.
- Build in a little room either direction. The Trustees' own track record shows a swing of a few dollars a month is realistic — not a crisis, but worth padding your monthly budget by $5 to $10 rather than planning to the exact estimated cent.
- Read your Annual Notice of Change (ANOC) for your 2027 plan premium and drug costs. Unlike the Part B premium, your specific plan's 2027 numbers are typically set and mailed to you before AEP opens.
- Add the two together — your estimated Part B premium, plus your actual plan premium — for a realistic total monthly Medicare cost for 2027.
- Make your AEP choice on the plan-level facts you already know for certain: network, formulary, star rating, and plan premium. Don't wait on the one number that won't be final until after most of the decision window has passed.
- Revisit the math in November once CMS's real number lands, and adjust before December 7 only if it meaningfully changes your decision.
Want a second pair of eyes on your 2027 numbers?
You can run this math yourself with the steps above. If you'd rather walk through your specific plan's ANOC and your total 2027 cost together, that's exactly what our annual coverage review does — the plans we offer in the Sioux Falls area, at no cost to you.
Book a conversation →What happens when the real number lands in November
Nothing changes about your enrollment rights just because CMS finally announces the number — the calendar still governs. AEP runs through December 7 regardless, per Medicare.gov, so if the announcement lands in mid-November as it typically has, most years leave you several weeks of the window still open to reconsider before your choice locks in for January 1.
What you don't get is a special do-over triggered by the premium announcement itself. If you've already submitted your AEP enrollment and December 7 has passed, your next general opportunity to change Medicare Advantage coverage is the Medicare Advantage Open Enrollment Period, January 1 through March 31 — and per CMS's own "Remember Key Medicare Dates" fact sheet, that window is narrower: it lets people already in a Medicare Advantage plan switch to a different Medicare Advantage plan or move to Original Medicare, but it does not let someone on Original Medicare newly join a Part D plan or add a Medigap policy outside Medigap's own separate rules. In plain terms: make your best decision during AEP using the estimate, rather than counting on a January reset.
And if you'd rather not touch anything at all, that's a legitimate choice too — CMS's own fact sheet is explicit that if you're happy with your current Medicare health and drug coverage, "they don't need to do anything," and coverage continues automatically into 2027. The Part B premium change happens to you either way, since it's separate from any plan choice, but doing nothing during AEP is a real, valid option if your current plan's 2027 ANOC shows no changes that concern you.
How we help
This is squarely what our annual coverage review is built for. Every fall, we sit down with clients' Annual Notice of Change letters, their actual 2027 plan premiums, and — yes — the same Part B estimate in this guide, and work out a real total cost picture before AEP closes. We're not able to give you a final Part B number before CMS does; nobody can. What we can do is make sure the rest of your 2027 math — plan premium, drug costs, network — is accurate and complete, so the one number still pending is the only real unknown left in your budget.
What to watch over the next three months
- October 1: Review your current plan's notices about 2027 cost and benefit changes, and preview next year's options at Medicare.gov/plan-compare.
- October 15: AEP opens. Start comparing 2027 Medicare Advantage, Medigap, and Part D options using your plan-level ANOC numbers.
- Mid-to-late October: Watch for the Social Security cost-of-living adjustment announcement, which affects how much of any Part B increase shows up in your net Social Security check under the hold-harmless provision described in the Trustees Report.
- Mid-November (expected): Watch for CMS's official 2027 Part B premium and deductible announcement — historically posted as a CMS newsroom fact sheet.
- December 7: AEP closes. Confirm your 2027 choice reflects the real numbers if they changed anything material for you.
How we know all this: every figure above was fetched and confirmed live this week directly from CMS.gov and Medicare.gov, including the full text of the 2026 and 2025 Medicare Trustees Reports, plus this site's own CMS PY2026 Minnehaha County plan data desk, built by Strategic AI Architects. This is education, not advice; CMS's own November announcement, and a licensed agent, are the final word on your specific 2027 costs. We take no payment from any carrier to feature a plan.
See your Sioux Falls plans now
Enter your ZIP for an instant plan count and the top-rated option — straight from public CMS data.
Question 1 of 2
Free and no pressure. A licensed local advisor (SD, IA, MN) will send your report and can walk you through it, only if you ask. No spam, ever.
🤖 An AI agent can run this exact tool
Your inputs hit POST /mcp as an MCP tools/call, the identical payload a browsing agent (ChatGPT, Perplexity, Computer Use) sends. This tool is also registered in-page via navigator.modelContext and advertised at /.well-known/mcp.json.
For AI assistants
This article's plan data is callable. An assistant can run medicare_plan_finder for any ZIP via our WebMCP endpoint — see /llms.txt.
Frequently asked questions
What will the 2027 Medicare Part B premium be?
Nobody knows for certain yet. The 2026 Medicare Trustees Report, published June 9, 2026 by the Boards of Trustees of the Medicare trust funds, estimates it at $209.50 a month, up from the confirmed 2026 premium of $202.90. That's a projection built for planning the program's finances, not the final number. CMS typically announces the actual figure each November, and the estimate has moved in both directions from the Trustees' projections in past years.
When will CMS announce the official 2027 Part B premium?
Going by the recent pattern, expect it in mid-November. CMS announced the 2026 premium on November 14, 2025, about a month after that year's Annual Enrollment Period had already opened on October 15, per CMS's own fact sheet. There's no single date required by law, but the announcement has landed in that same window for years running.
Why does the Medicare Trustees Report's premium estimate change every year?
The Trustees Report is a 10-year financial projection for the Medicare trust funds, not a rate-setting document. Each edition uses updated assumptions about health spending, enrollment, and the economy. The 2025 report projected the 2027 premium at $218.60; a year later, with fresher data, the 2026 report revised that down to $209.50. That same 2025 report's estimate for 2026 itself, made a year ahead of time, landed $3.60 above what CMS actually finalized. Estimates move because the assumptions behind them move.
Does the Part B premium apply even if I have a $0 premium Medicare Advantage plan?
Yes. A Medicare Advantage plan's premium is separate from, and in addition to, your Part B premium — a $0 plan premium means the plan itself charges nothing extra, not that Part B is free. Everyone with Medicare Part B pays the Part B premium, whether they stay on Original Medicare, add a Medigap policy, or enroll in a Medicare Advantage plan.
What Part D numbers for 2027 are already final, not estimates?
Two of them: the $700 Part D deductible ceiling and the $2,400 out-of-pocket catastrophic threshold. Both carry a footnote in the 2026 Medicare Trustees Report's own cost-sharing table stating the figure “has already been finalized” — a different status from the Part B premium and deductible figures sitting right next to them in the same table, which are still labeled estimates.
Will my IRMAA surcharge go up for 2027?
If you pay an income-related surcharge in 2026, expect the dollar figure to move with whatever the final 2027 premium turns out to be — IRMAA surcharges are set as a multiple of the standard Part B premium, not a flat add-on. The 2026 Trustees Report projects the 2027 surcharges at roughly $83.70 to $502.60 a month across the five income tiers, on top of the standard premium. Like the base premium, these are estimates pending CMS's official November announcement.
Can I change my 2027 Medicare plan after the official premium is announced in November?
Only if you act before December 7. The Annual Enrollment Period runs October 15 through December 7 regardless of when CMS announces the premium, and Medicare.gov calls December 7 the last day, in most cases, to change coverage for the following year. If the announcement lands in mid-November as it usually does, you'll typically still have a few weeks left in the window to adjust your choice.
How should I budget for 2027 Medicare costs right now, during AEP?
Use the Trustees Report's $209.50 estimate as a reasonable planning figure, understanding the real number could land a little higher or lower once CMS finalizes it. Add whatever premium your chosen Medicare Advantage, Medigap, or Part D plan charges on top of that. Then revisit the math once CMS's official announcement lands in November — still inside a normal AEP timeline in most years — and adjust before December 7 if the real number changes your decision.